YEL — entrepreneur's pension insurance
YEL — yrittäjän eläkevakuutus — is the entrepreneur’s pension insurance. It funds your future pension, sick pay, and parental leave. For a Finnish toiminimi above a certain income floor it’s mandatory, not optional. This page covers what GigBooks tracks for you, the calculator inside the app, and what’s still on you to do externally.
When YEL is required
You must take out YEL if all of these are true:
- You’re 18–67 (the age range shifts slowly upward over time).
- You’ve worked as an entrepreneur continuously for at least four months.
- Your estimated annual entrepreneurial work income (työtulo) is at or above the YEL floor.
The 2026 floor is €9,423.09 per year of confirmed work income. The figure is set yearly and reaches this page and the app from the same rule set, so the dashboard always shows the current value.
If your projected platform income is under the floor, YEL isn’t compulsory yet — but the moment you cross it, the four-month clock matters.
What “työtulo” actually means
This is the trickiest part of YEL for new entrepreneurs. YEL income is not your turnover and not your taxable profit. It’s a notional figure that should reflect what your work would earn as a comparable employee.
- For a courier doing 30+ hours a week year-round, a sensible työtulo is somewhere in the €18,000–€30,000 range — broadly the salary an employee in similar work would earn.
- For a part-time tutor doing 4 hours a week, your työtulo might legitimately be much lower than your invoice total — most of those hours don’t count as full work.
You declare your työtulo when you take out YEL. Your pension provider can challenge it if it’s wildly out of step with reality, and you can update it as your work changes (we recommend reviewing it annually).
GigBooks gives you signals — your annualised platform earnings, your hours worked from logged shifts — but the final declared income is something you set with your pension provider.
The YEL calculator
In Tax → Social insurance, GigBooks has a stateless calculator that takes a yearly income and shows:
- The monthly contribution at the standard rate for your age band.
- The monthly contribution with first-year discount if you’re in your first 48 months as an entrepreneur (a 22% discount today).
- The annual benefits the contribution buys you: estimated daily sick pay, monthly parental allowance, and projected monthly pension at retirement.
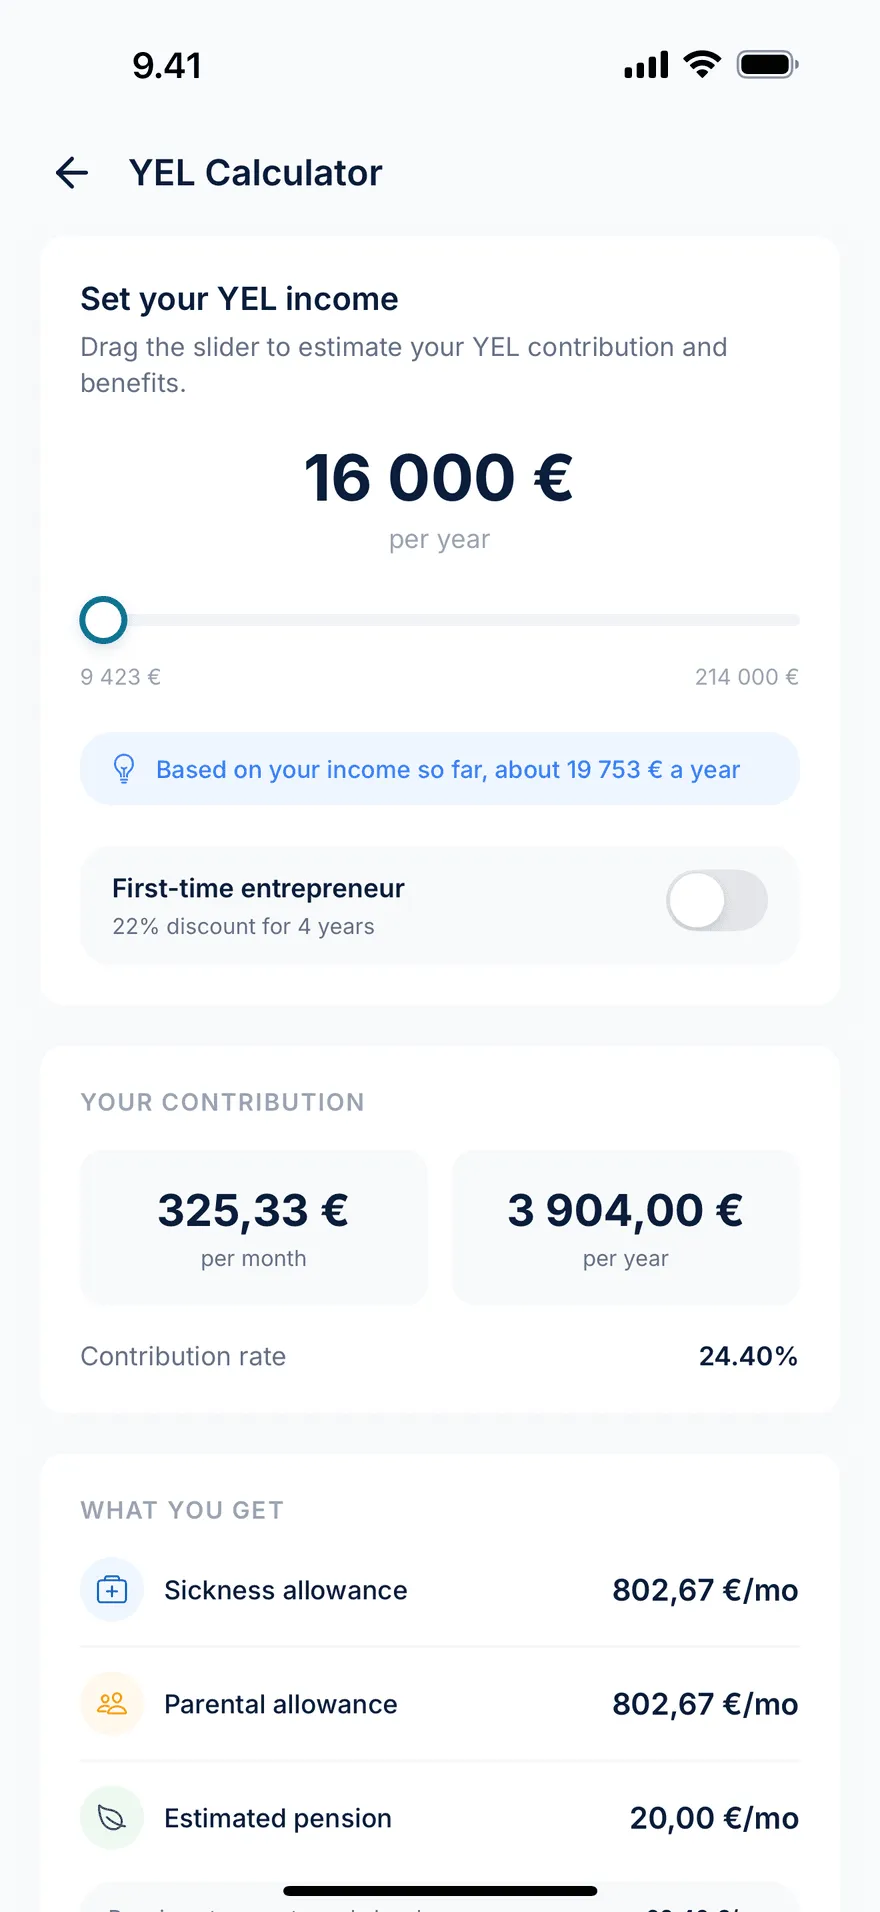
Tap the slider or type a number — the calculator runs in real time so you can compare scenarios.
YEL run-rate on the dashboard
The dashboard shows your YEL run-rate as the projected annual entrepreneurial earnings, based on your last 90 days of recorded income. Two scenarios get a visible alert:
- You’re under the floor but trending towards it. The card says “approaching YEL floor” with the projected crossing date.
- You’re above the floor and you haven’t yet recorded a YEL contribution. The card says “YEL income not configured” with a link to the setup sheet.
The run-rate is always indicative — your work patterns can change. Use it as a prompt to think, not as a hard rule.
The setup sheet
The setup checklist’s YEL configured step opens a sheet where you record what you’ve actually agreed with your pension provider:
- Confirmed YEL income — the työtulo on your YEL contract today.
- Monthly contribution — what you actually pay each month.
- First year — whether you’re in the first-year discount window.
Or, if YEL doesn’t apply yet (you’re under the floor and not required), tap Not applicable. You can revisit this any time from Settings → Business.
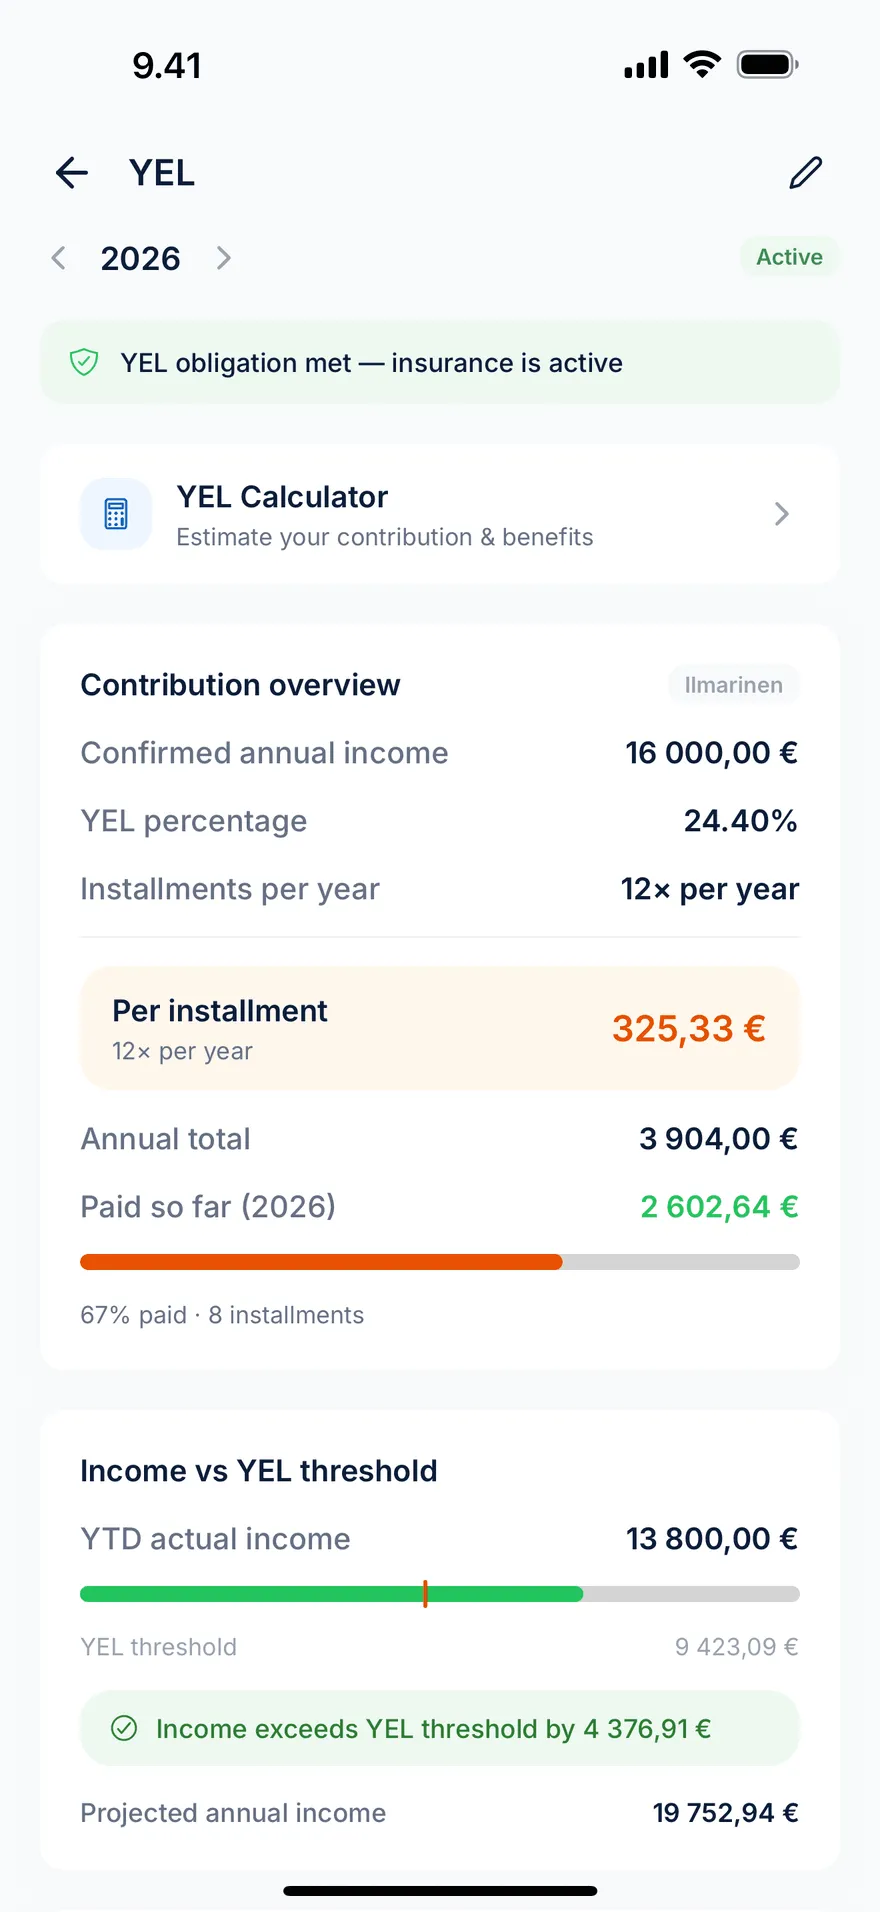
Once configured:
- Your monthly contribution shows up as a recurring expected expense — when the bank import sees the actual debit from your provider, it auto-matches.
- Your dashboard’s compliance card updates from “incomplete” to “on track”.
- Your annual tax-return draft includes the right YEL deduction.
YEL and your tax return
Your YEL contributions are deductible on your personal tax return. GigBooks tracks the year’s contributions as recurring expenses tagged YEL, and the annual tax-return draft picks them up automatically.
This is one of the larger deductions for a typical platform worker — €4,000–€8,000 a year of tax-deductible expense — so it matters that it’s recorded correctly.
What GigBooks will not do
- Sell or quote YEL insurance. You buy it from a pension insurance company. The four major Finnish providers are Varma, Ilmarinen, Elo, and Veritas.
- Negotiate your työtulo with your provider. GigBooks suggests a sensible range based on your work; the conversation about declared income is between you and your provider.
- Make YEL payments. You set up a direct debit (or pay manually) with your provider. GigBooks reconciles when the payment lands in your bank.
Common situations
You’re a part-time courier with a day job. Your day job has TyEL (employee pension), so YEL only applies to the entrepreneurial side. The calculator helps you set a realistic, lower työtulo that covers just your platform work.
You’re at the YEL floor for the first time. Take out YEL within four months of crossing the floor. The first-year discount applies for 48 months from the start of your first entrepreneurial activity, so taking YEL out earlier is usually cheaper.
You’re between platforms or seasons and earnings drop. You can adjust your declared työtulo with your provider mid-year. If you go below the floor and stay there, you can lift the YEL obligation entirely. GigBooks’s run-rate makes the change easier to spot.
Next
- Advance tax — paying income tax in instalments based on your projected year.
- Deduction calculator — estimate the effect of deductible expenses using your chosen tax rate.